The charge appears small enough to ignore, then it renews again. A store advertises a price that evaporates at the register. A collector calls at odd hours and refuses to explain the debt. A “free trial” becomes a maze of cancellation steps designed to exhaust you. Most people pay once out of fatigue. That is how unfair practices survive.
Consumer protection laws exist to limit deception, hidden terms, and abusive collection tactics in the marketplace. They are not a promise that every annoying business practice is illegal, and remedies still depend on facts, contracts, and local rules. This guide shows how to spot common red flags and how to respond with records, deadlines, and the right escalation path. It is general education, not legal advice about your purchase or account. For a significant loss, speak with a consumer attorney or legal-aid program where you live.
What Consumer Protection Rules Usually Target
Consumer protection law is a cluster of statutes, regulations, and enforcement programs rather than a single rulebook. At the federal level in the United States, agencies such as the Federal Trade Commission and the Consumer Financial Protection Bureau police many deceptive acts, unfair practices, and specific markets like credit and debt collection. States add their own consumer-protection statutes, often called “little FTC acts,” and state attorneys general regularly take complaints. Industry-specific rules cover cars, lending, telemarketing, warranties, and online subscriptions with different details.
The common theme is commercial fairness in the transaction itself: truthful advertising, clear material terms, honorable billing, and collection conduct that stays inside legal limits. A product can be disappointing without being unlawful. A seller can drive a hard bargain without crossing the line. The legal problem usually appears when a business misleads you about a key fact, buries mandatory charges, refuses promised cancellations, or uses tactics that statutes specifically forbid.
Unfair, Deceptive, and Abusive in Plain Terms
Deceptive practices involve misleading claims or omissions that matter to a reasonable buyer’s decision. Unfair practices can include conduct that causes substantial injury consumers cannot reasonably avoid and that is not outweighed by benefits to consumers or competition, under standards used in federal enforcement. Abusive conduct appears in some financial-protection contexts when a company interferes with a consumer’s understanding or takes unreasonable advantage of reliance or inability to protect interests. You do not need perfect labels to start a dispute. You need a clear story about what was promised, what was delivered, and how you were charged.
How to Spot Unfair Practices Before and After You Pay
Pressure is a warning sign. “Today-only” pricing that never ends, refusal to put terms in writing, and scripts that discourage questions deserve skepticism. Compare the advertised price with the checkout total. Read auto-renewal language, cancellation steps, return windows, and arbitration clauses before you click agree. If a salesperson’s verbal promise is the reason you buy, ask for it in an email or on the contract face. Spoken assurances fade. Written terms decide most disputes.
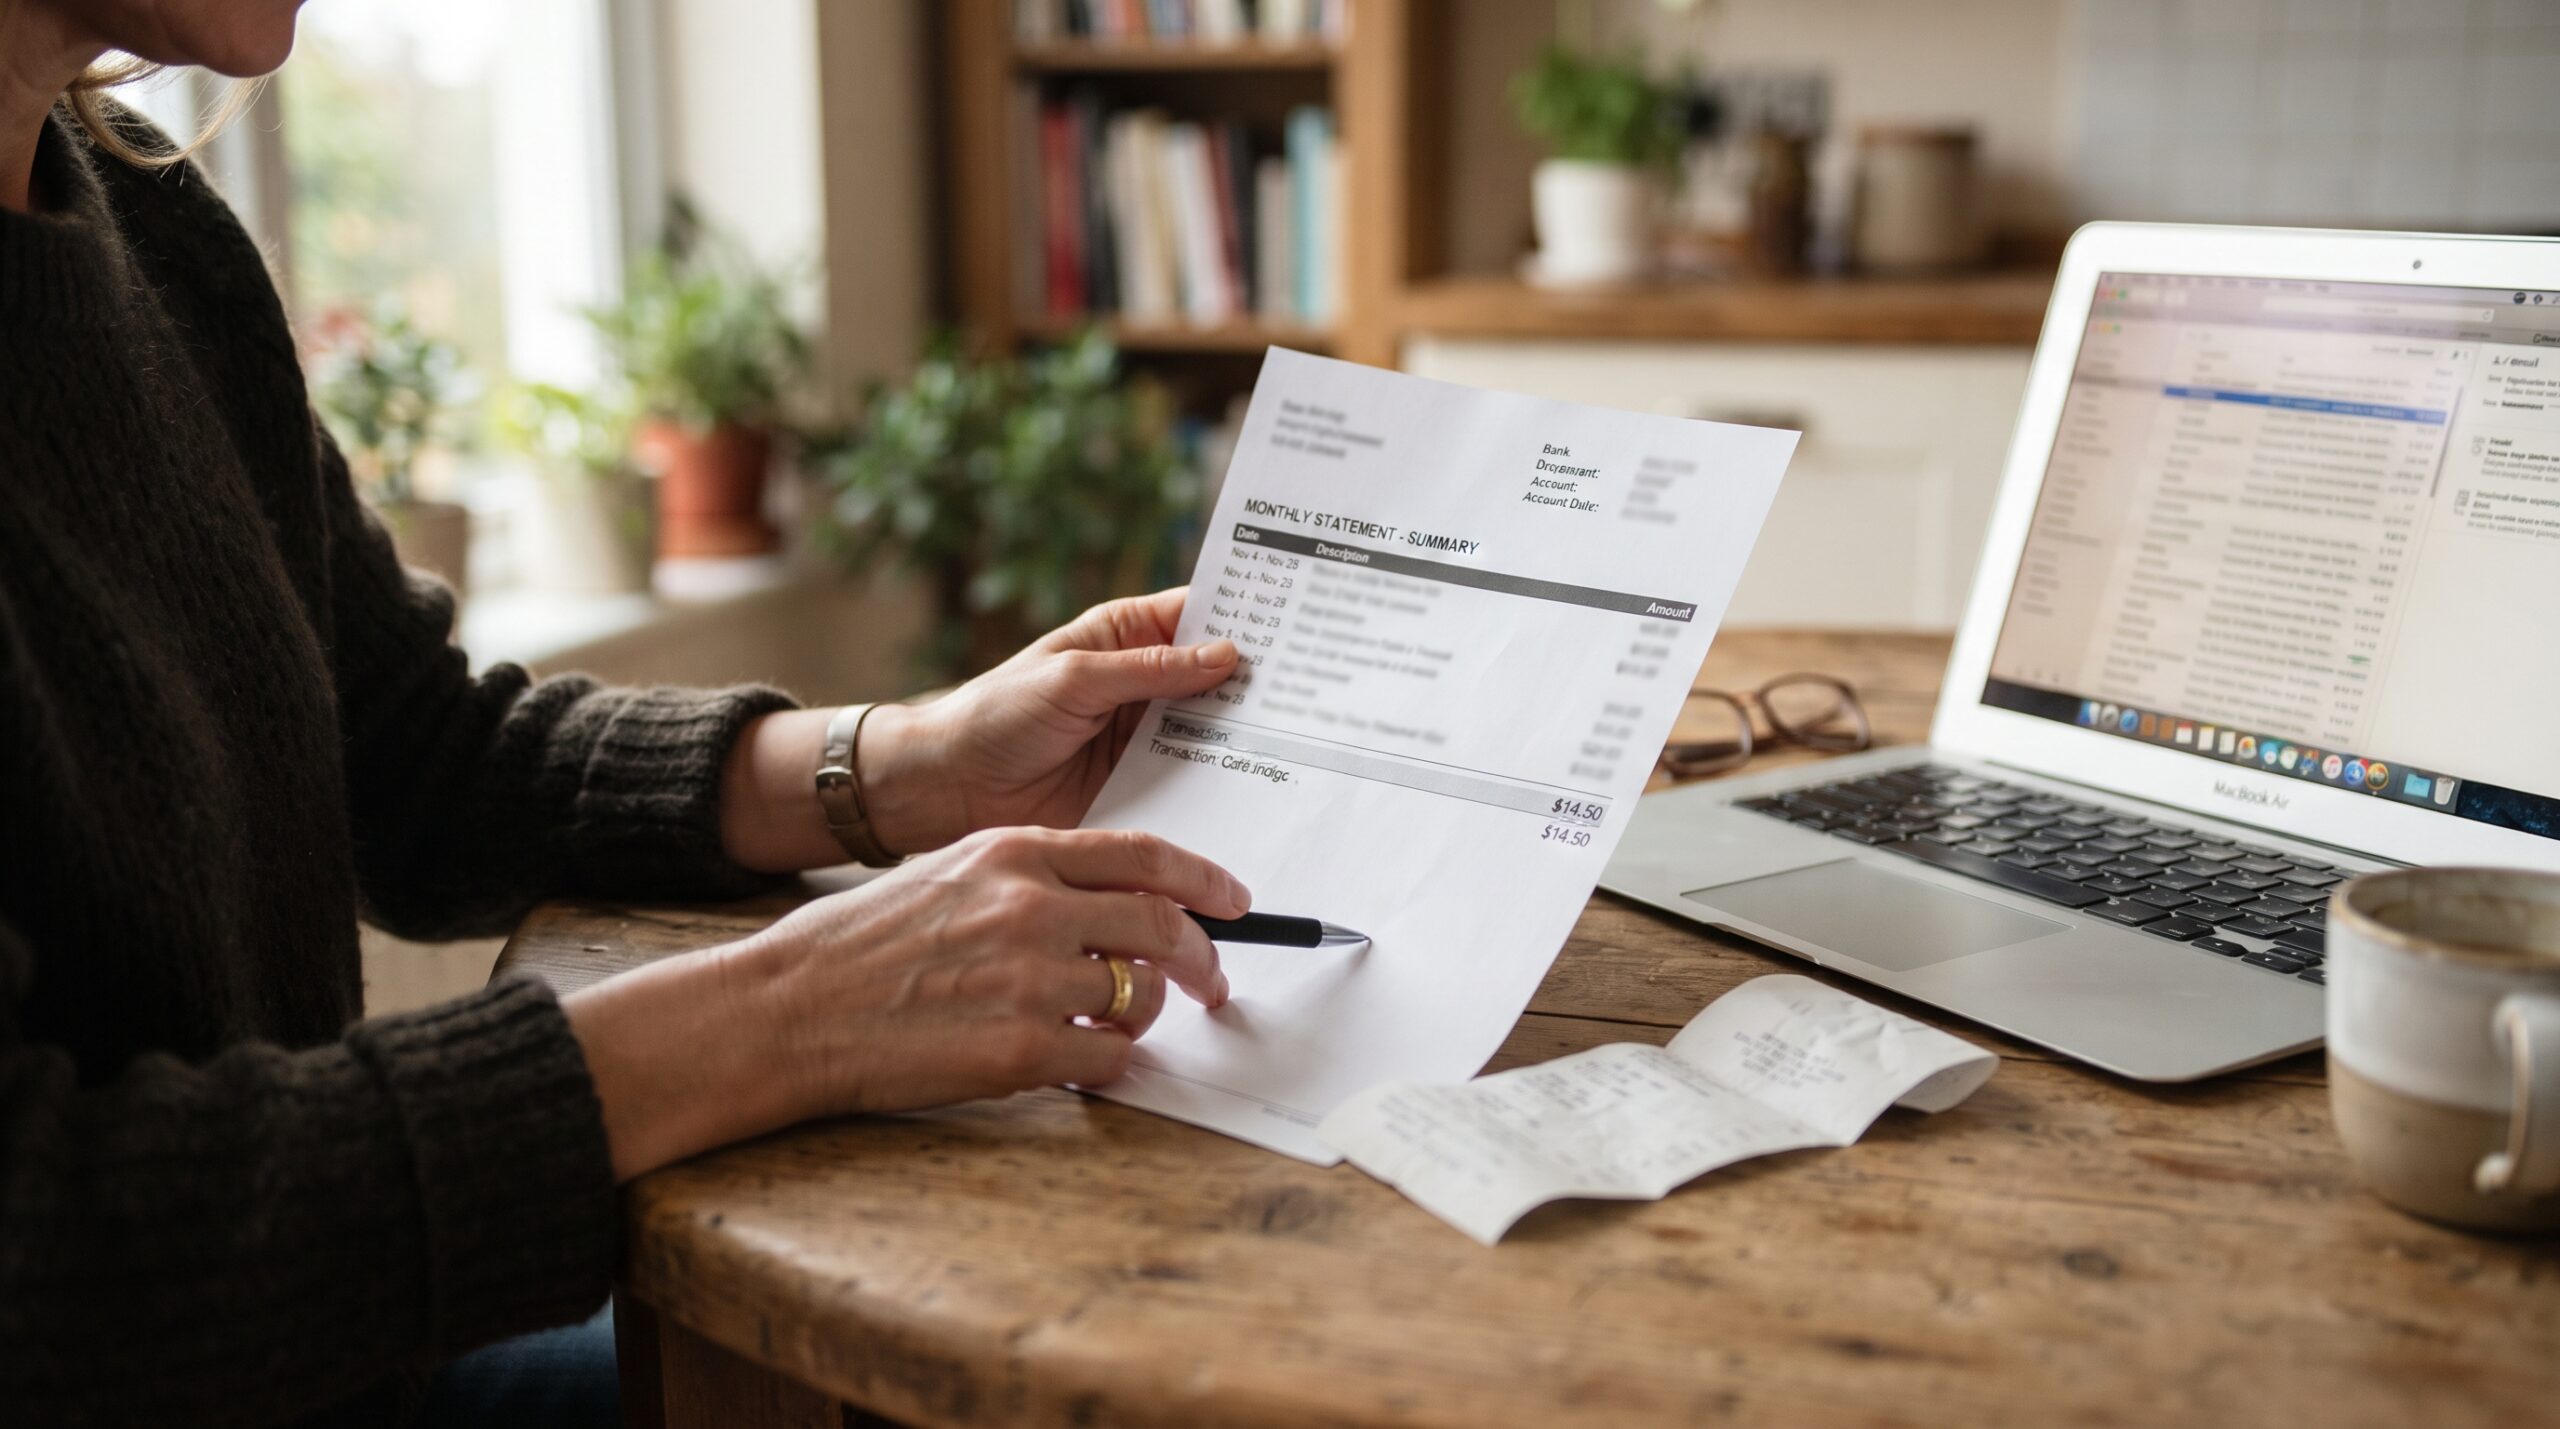
After the purchase, watch the first billing cycle closely. Unexpected side charges, repeated trial conversions, and accounts you cannot cancel through the same channel you used to sign up are classic friction tactics. Save confirmation pages, chat transcripts, and shipping records. Take screenshots of ads that later disappear. When a company changes the deal after payment, your contemporaneous records become the spine of any complaint.
Debt Collection and Credit Red Flags
Collectors generally must identify themselves, avoid harassment patterns banned by law, and refrain from false threats about arrest or immediate seizure for ordinary consumer debts. You may request validation of a debt in writing under applicable federal rules and related state protections. Keep a call log with dates and summaries. If the debt is not yours, say so in a dated letter and keep proof of mailing. Credit-report errors have separate dispute channels through the bureaus and the furnishers of information. Do not ignore notices simply because the amount seems too small to fight; small errors compound.
First Responses That Preserve Your Leverage
Start with a tight written complaint to the company. State the product or service, the date, the amount, what you were told, what went wrong, and the exact remedy you want: refund, cancellation, repair, or corrected reporting. Attach copies of key documents, not your only originals. Set a reasonable response date. Written escalations create a timeline that card issuers, regulators, and courts understand better than a long phone argument with a rotating call center.
If you paid by credit card, review billing-dispute and chargeback options quickly, because issuer windows can close. Bank transfers and cash leave fewer recovery levers. For subscriptions, cancel through every required channel the terms name, then confirm in writing that no further billing is authorized. If a merchant ignores cancellation, your paper trail supports disputes with the payment provider and complaints to agencies.
Negotiation Without Giving Away the Case
Be firm and factual. Avoid exaggerated claims you cannot prove. Do not send angry messages that invent threats. If a company offers a partial refund, evaluate it against the cost of further escalation and the strength of your documents. A partial recovery now is sometimes wiser than a perfect claim you will not have time to pursue. When the amount is large or the conduct is systemic, pause before you accept a low offer and get advice.
Escalation Paths: Agencies, Credit Bureaus, and Courts
If the company stonewalls, file complaints with the state attorney general’s consumer division, the FTC’s complaint system, and, for many financial products, the CFPB. These filings create intelligence for enforcement even when they do not produce an instant personal payout. Licensing boards regulate certain trades and can pressure bad actors through credentials. Better Business Bureau-style platforms are informal; use them as one channel, not your only strategy.
Small-claims court can be a practical tool for modest losses when your records are clean and the defendant is identifiable. Read the monetary limits, filing fees, and service rules for your local court. Arbitration clauses in contracts may require a different forum, which is why reading dispute-resolution terms early matters. For patterns affecting many buyers, consumer class actions and public enforcement exist, yet individual relief still often begins with your own complaint file.
Warranties and “As Is” Reality
Many goods come with implied warranty protections under state law unless validly disclaimed in the manner statutes allow, alongside any express warranty the seller made. “As is” language can limit remedies in some transactions and not in others, especially where consumer statutes restrict disclaimers. Keep the warranty booklet, service records, and repair refusals. A seller who promises repairs in writing has created expectations you can document even when a website banner later changes tone.
Building a Consumer Complaint File That Works
Organize one folder with the ad, the contract, proof of payment, cancellation attempts, and the company’s responses. Write a one-page chronology with dates. Calculate the exact dollars at issue, including fees and shipping if they are part of the claim. Name the people you spoke with when you have that information. Clean files get better outcomes from card disputes, regulators, and volunteer lawyers reviewing intake.
Watch limitation periods for lawsuits and the shorter administrative windows for chargebacks and credit disputes. Act while the trail is warm. If a business uses a brand name that differs from its legal entity, capture both from receipts and websites. Suing or serving the wrong name wastes months. When the other side has counsel, consider getting your own before you “explain everything” in a long letter that admits facts you do not intend to concede.
A Practical Standard We Use Mentally
Ask three questions. What exact representation or duty was broken? What proof shows it? What remedy is proportional and available through the channel you are using? If you cannot answer those questions, gather more documents before you escalate. Clarity beats volume. A two-page complaint with exhibits often outperforms a ten-page rant without attachments.
FAQ
What are consumer protection laws?
Rules that restrict deceptive, unfair, and certain abusive commercial practices and that provide complaint, enforcement, and private-remedy avenues depending on the statute and jurisdiction.
How do I spot unfair business practices?
Compare ads to checkout totals, read renewal and cancellation terms, pressure-test verbal promises in writing, and watch for billing you did not authorize or cannot stop through normal channels.
What should I do first after a bad transaction?
Collect documents, send a written demand with a clear remedy and deadline, and review payment-provider dispute options before windows close.
Where can I file a complaint?
Company customer service first, then payment providers when applicable, state attorney general consumer offices, FTC complaint systems, CFPB for many financial products, and courts or arbitration as contracts and local law allow.
Can I sue in small claims court?
Often yes for amounts under local limits if you can identify and serve the defendant and your claim fits the forum. Contract terms may require arbitration instead.
Does complaining to the FTC get my money back automatically?
Not automatically. Agency complaints support enforcement and market monitoring; individual recovery more often comes from refunds, chargebacks, settlements, or private claims.
Is this article legal advice?
No. It is educational information only. Consumer remedies vary by product, contract, and location. Consult a qualified attorney about significant losses.
Fair Markets Depend on Consumers Who Document and Escalate
Consumer protection laws give you tools against deception, trap billing, and abusive collection, yet tools only work when you use them with proof and timing. Spot the mismatch between promise and charge. Write the company. Use payment disputes early. File agency complaints when merchants ignore legitimate demands. Choose small claims or counsel when the dollars justify the effort.
You cannot police every dark pattern alone. You can refuse to be an easy loss. Keep the receipts, cancel in writing, and escalate with a clean chronology. That habit recovers money, discourages repeat abuse, and turns a frustrating charge into a process you control.
Leave a Reply